In the previous article, we looked at the question of when real estate financing can actually be considered secure.
But even if the bank is generally prepared to finance the purchase, another important question arises:
How much of the buyer’s own money is actually required?
This is because the purchase price is not the only cost involved in acquiring property. Additional acquisition costs can easily amount to several tens of thousands of euros.
Let us use the following example:
Purchase price of the property: €500,000
Bank financing: €450,000
Difference to the purchase price: €50,000
At first glance, one might therefore assume that the buyer only needs €50,000 in equity.
That would be too simplistic.
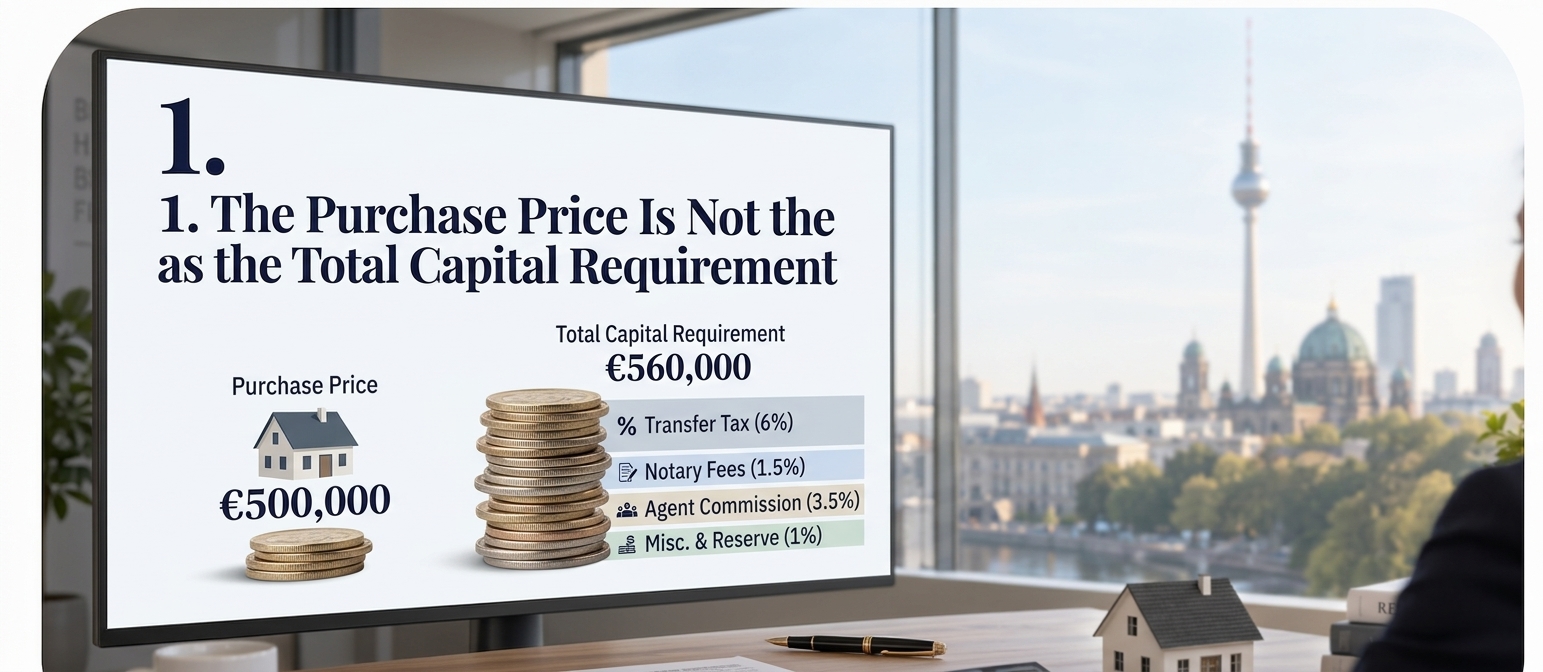
1. The purchase price is not the same as the total capital requirement
When buying property, additional costs arise on top of the purchase price.
These mainly include:
Real estate transfer tax
Notary fees
Land register fees
Costs for registering the mortgage charge
Where applicable, real estate agent commission
Where applicable, additional financing-related costs
These costs should ideally be taken into account before the financing application is submitted.
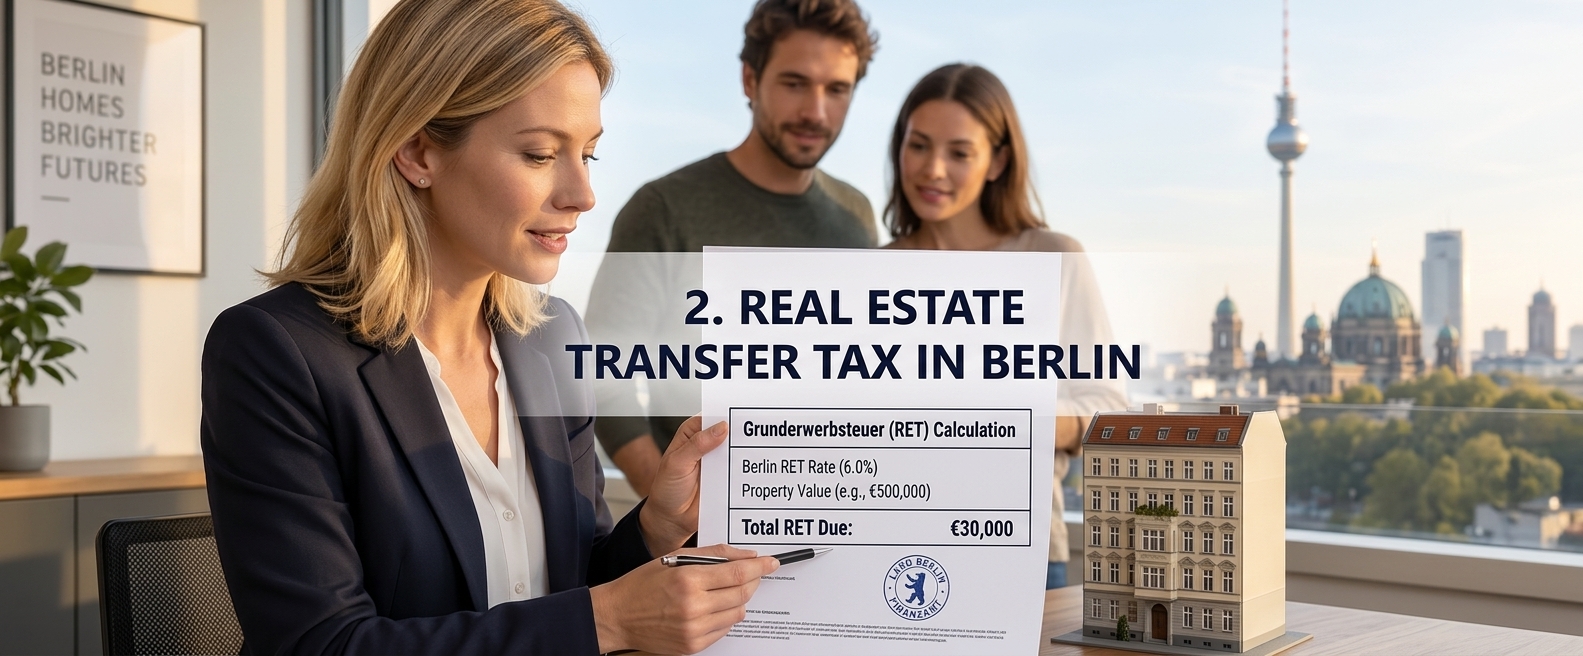
2. Real estate transfer tax in Berlin
In Berlin, the real estate transfer tax is currently 6% of the relevant consideration, which in a standard purchase is usually the purchase price.
For a purchase price of €500,000:
€500,000 × 6% = €30,000
The real estate transfer tax alone therefore results in additional costs of:
€30,000
This amount is added on top of the purchase price.
3. Notary and land register costs
A property purchase in Germany must be notarized.
Additional costs also arise at the land registry, for example for:
Registration of the priority notice
Transfer of ownership
Registration of the mortgage charge for the financing bank
Notary and land registry fees are regulated by law and depend, among other things, on the value of the transaction.
For an initial financing calculation, it is often reasonable to estimate approximately:
1.5% of the purchase price
for notary, land registry and the usual financing-related registrations.
In our example:
€500,000 × 1.5% = approximately €7,500
The actual amount may be slightly higher or lower depending on the purchase agreement, the amount of the mortgage charge and the specific registrations required.
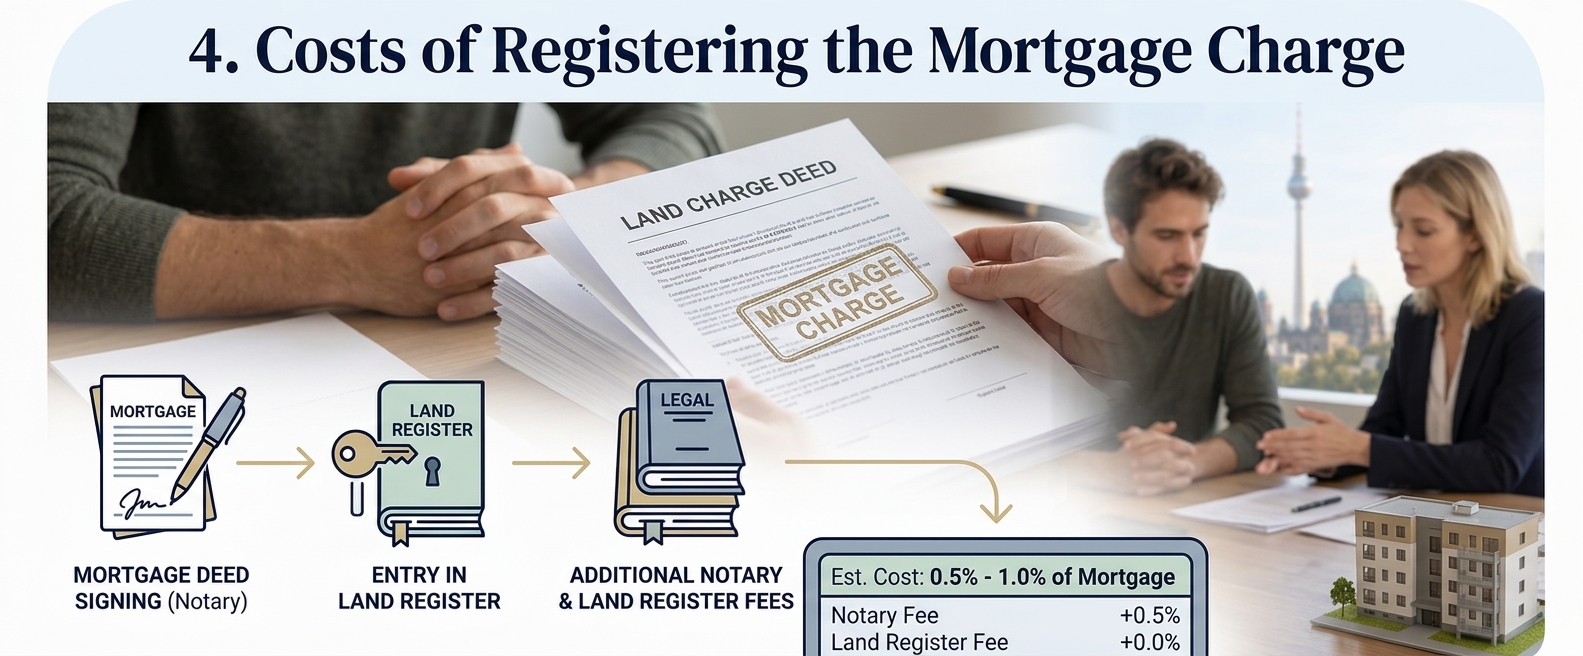
4. What does the mortgage charge cost?
For financing of €450,000, the bank normally requires security.
For this purpose, a mortgage charge (Grundschuld) is generally registered in favor of the bank in the land register.
The mortgage charge itself generates notary and land registry costs.
These costs are often included in the general estimate for notary and land register fees.
However, the important point for the buyer is:
The financing itself also creates additional costs.
5. What happens if a real estate agent is involved?
If the property is brokered by a real estate agent, an additional commission may be payable.
When a private individual purchases a condominium or single-family home in Germany, statutory rules apply to the allocation of brokerage costs.
The exact commission depends on the contractual arrangement.
For our example, let us assume a buyer’s share of:
3.57% including VAT
This would result in agent fees of:
€500,000 × 3.57% = €17,850
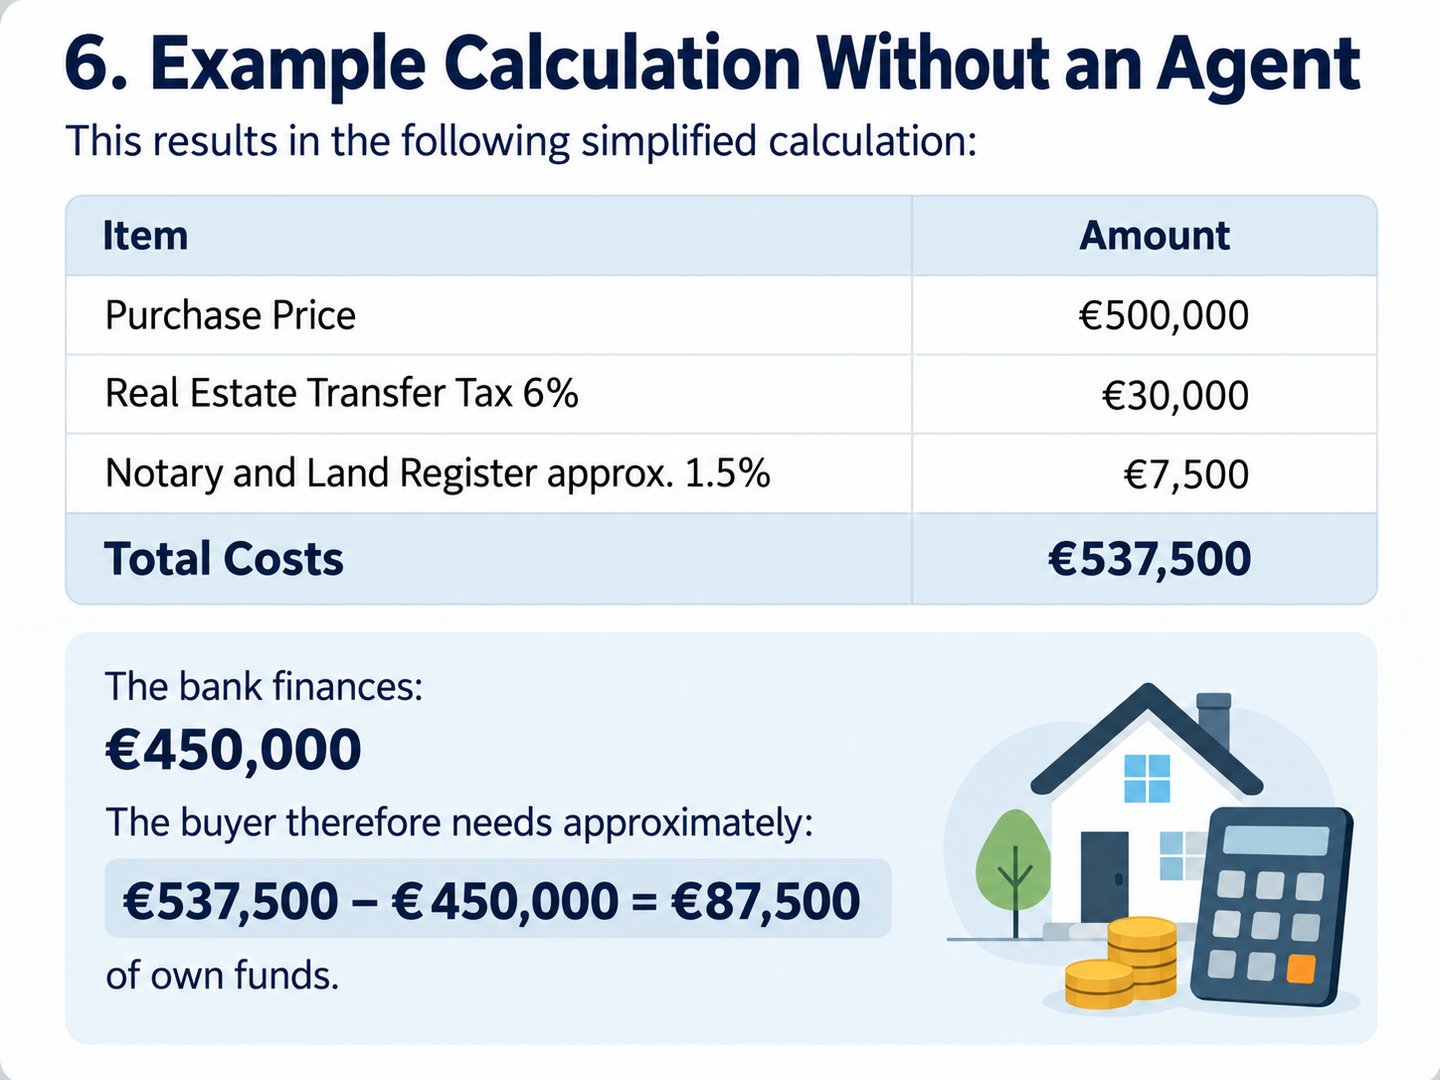
6. Example calculation without a real estate agent
This gives us the following simplified calculation:
Position
AmountPurchase price€500,000
Real estate transfer tax 6% €30,000
Notary and land register approx. 1.5% €7,500
Total cost€537,500
The bank finances:
€450,000
The buyer therefore needs approximately:
€537,500 – €450,000 = €87,500
in their own funds.
This means that although the difference between the purchase price and the bank loan is only €50,000, the actual capital requirement is approximately:
€87,500
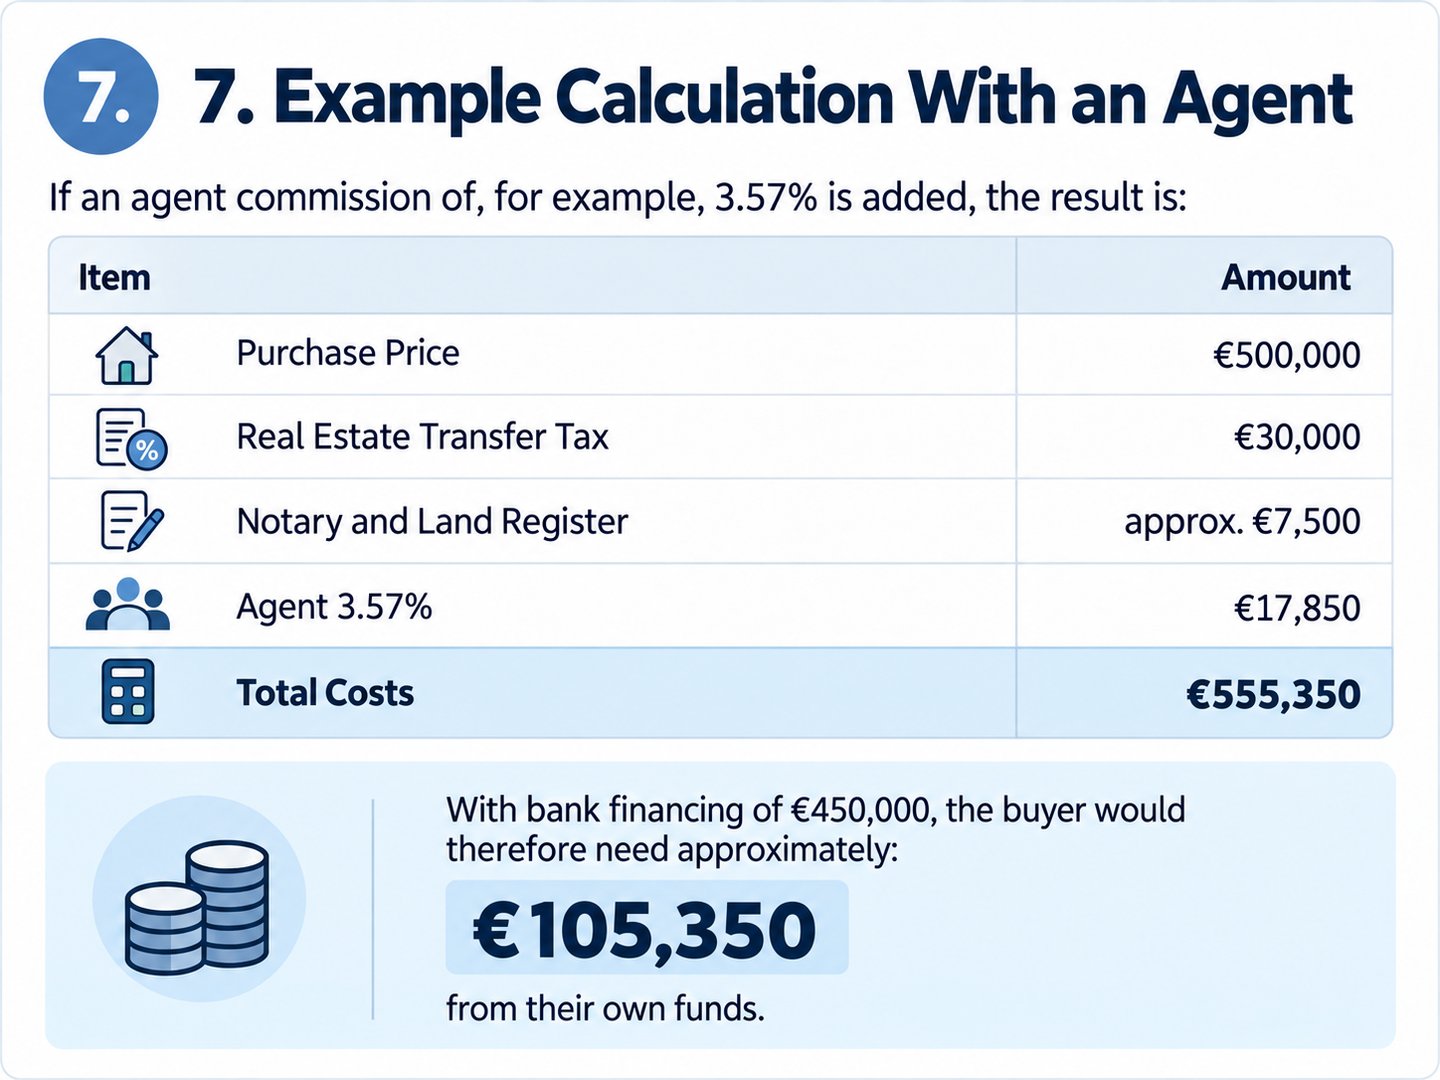
7. Example calculation with a real estate agent
If we additionally assume an agent commission of 3.57%, the calculation becomes:
PositionAmount
Purchase price €500,000
Real estate transfer tax €30,000
Notary and land registerapprox. €7,500
Real estate agent 3.57% €17,850
Total cost€555,350
With bank financing of €450,000, the buyer would therefore need approximately:
€105,350
from their own funds.
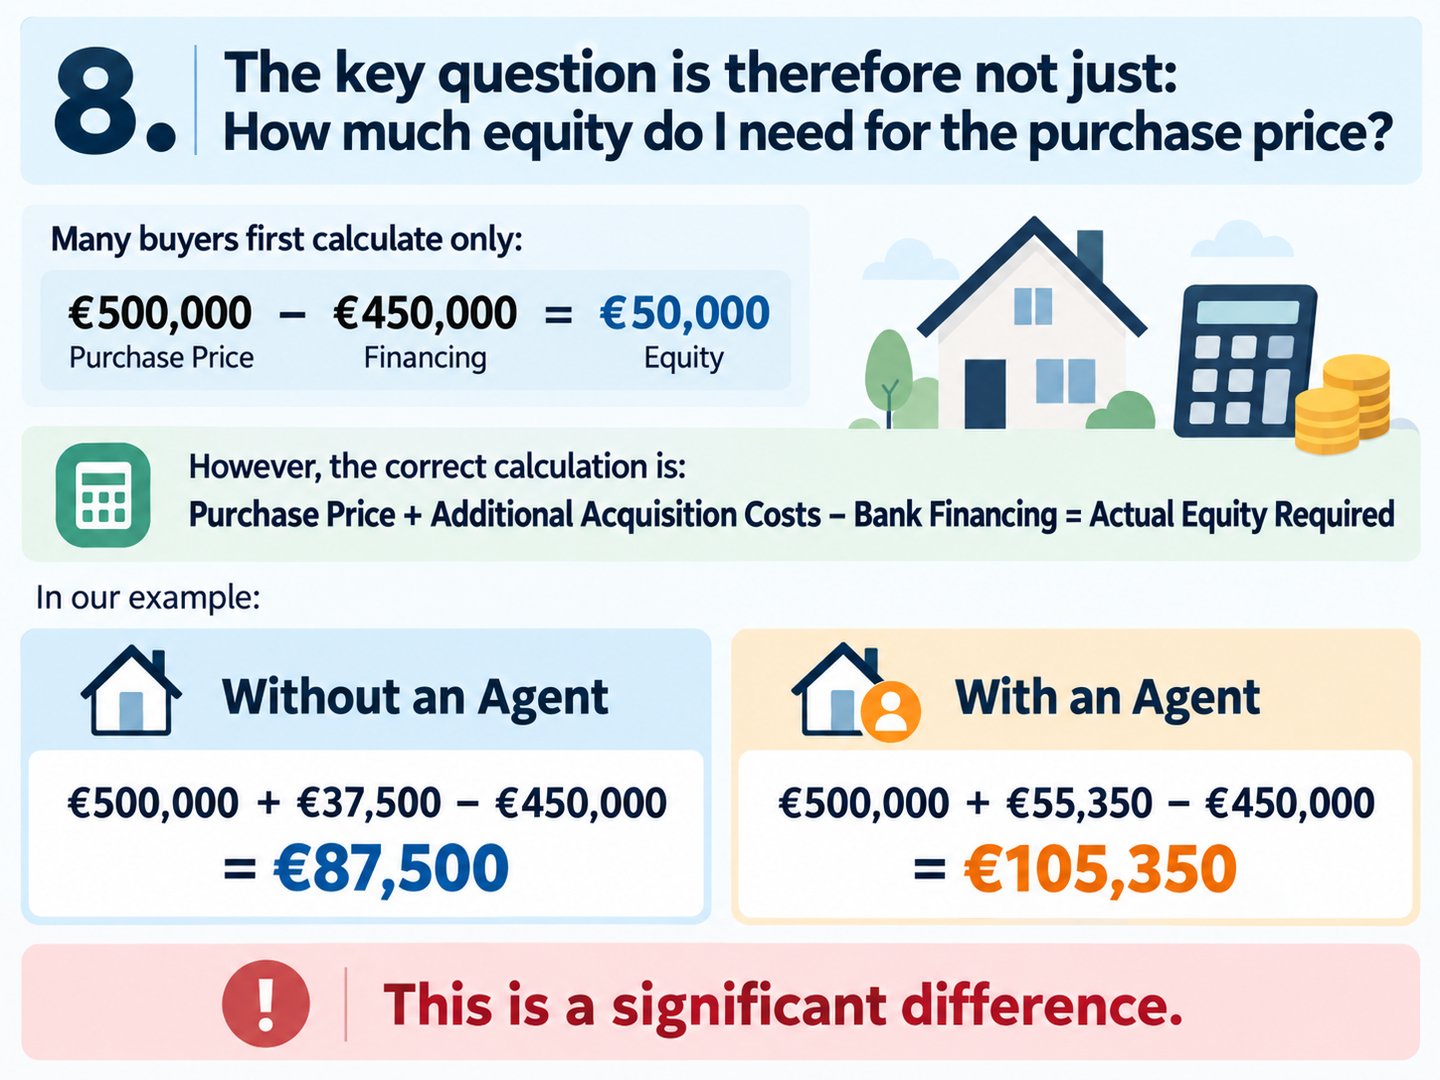
8. The key question is therefore not only: How much equity do I need for the purchase price?
Many buyers initially calculate:
€500,000 purchase price – €450,000 financing = €50,000 equity
But the more accurate calculation is:
Purchase price + additional acquisition costs – bank financing = actual equity requirement
In our example:
Without a real estate agent
€500,000 + €37,500 – €450,000 = €87,500
With a real estate agent
€500,000 + €55,350 – €450,000 = €105,350
That is a substantial difference.
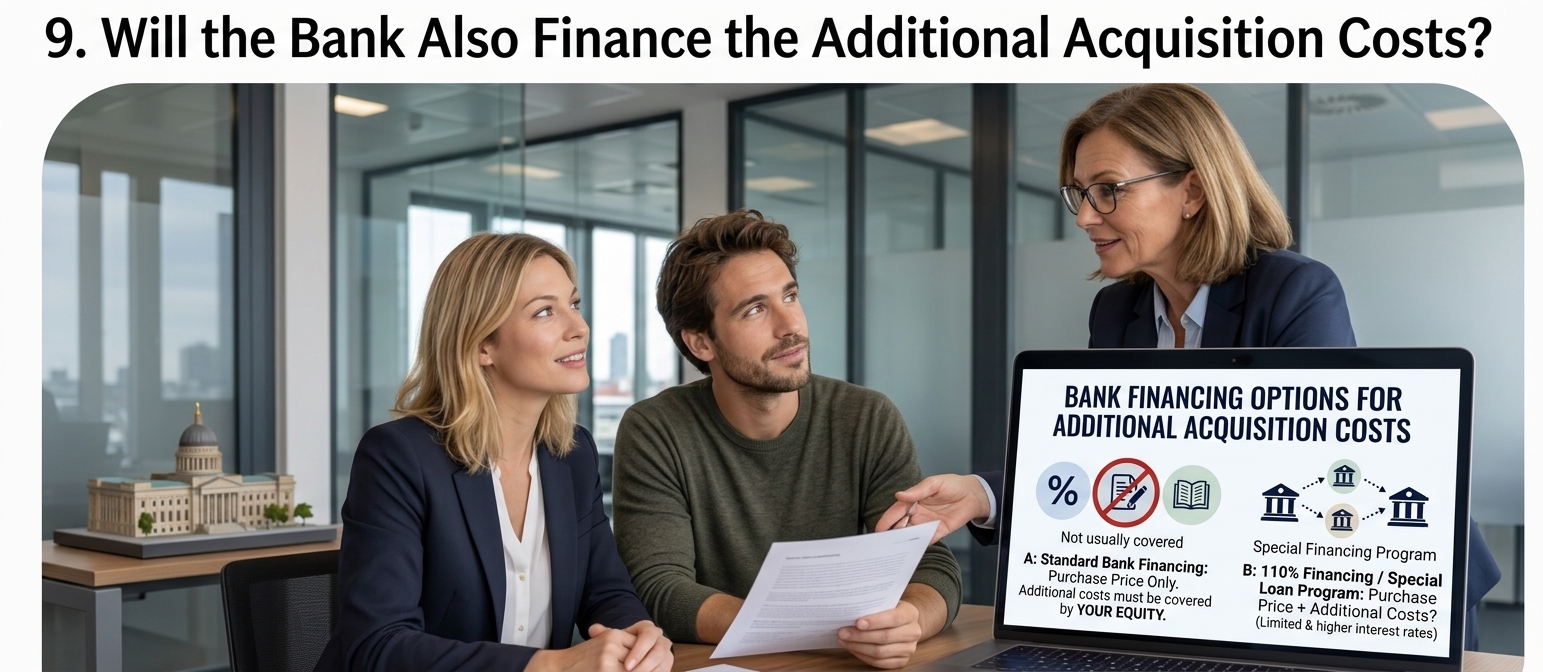
9. Will the bank also finance the additional costs?
In principle, financing structures are possible in which a very high percentage of the purchase price, or even more than the purchase price, is financed.
Whether a bank is willing to do this depends on factors such as:
The buyer’s income
Creditworthiness
Existing assets
The value of the property
The relationship between the loan amount and the property value
Existing financial obligations
The higher the financing compared with the value of the property, the higher the bank’s risk usually becomes.
For this reason, many banks expect the buyer to cover at least the acquisition costs, or a substantial part of them, from their own funds.
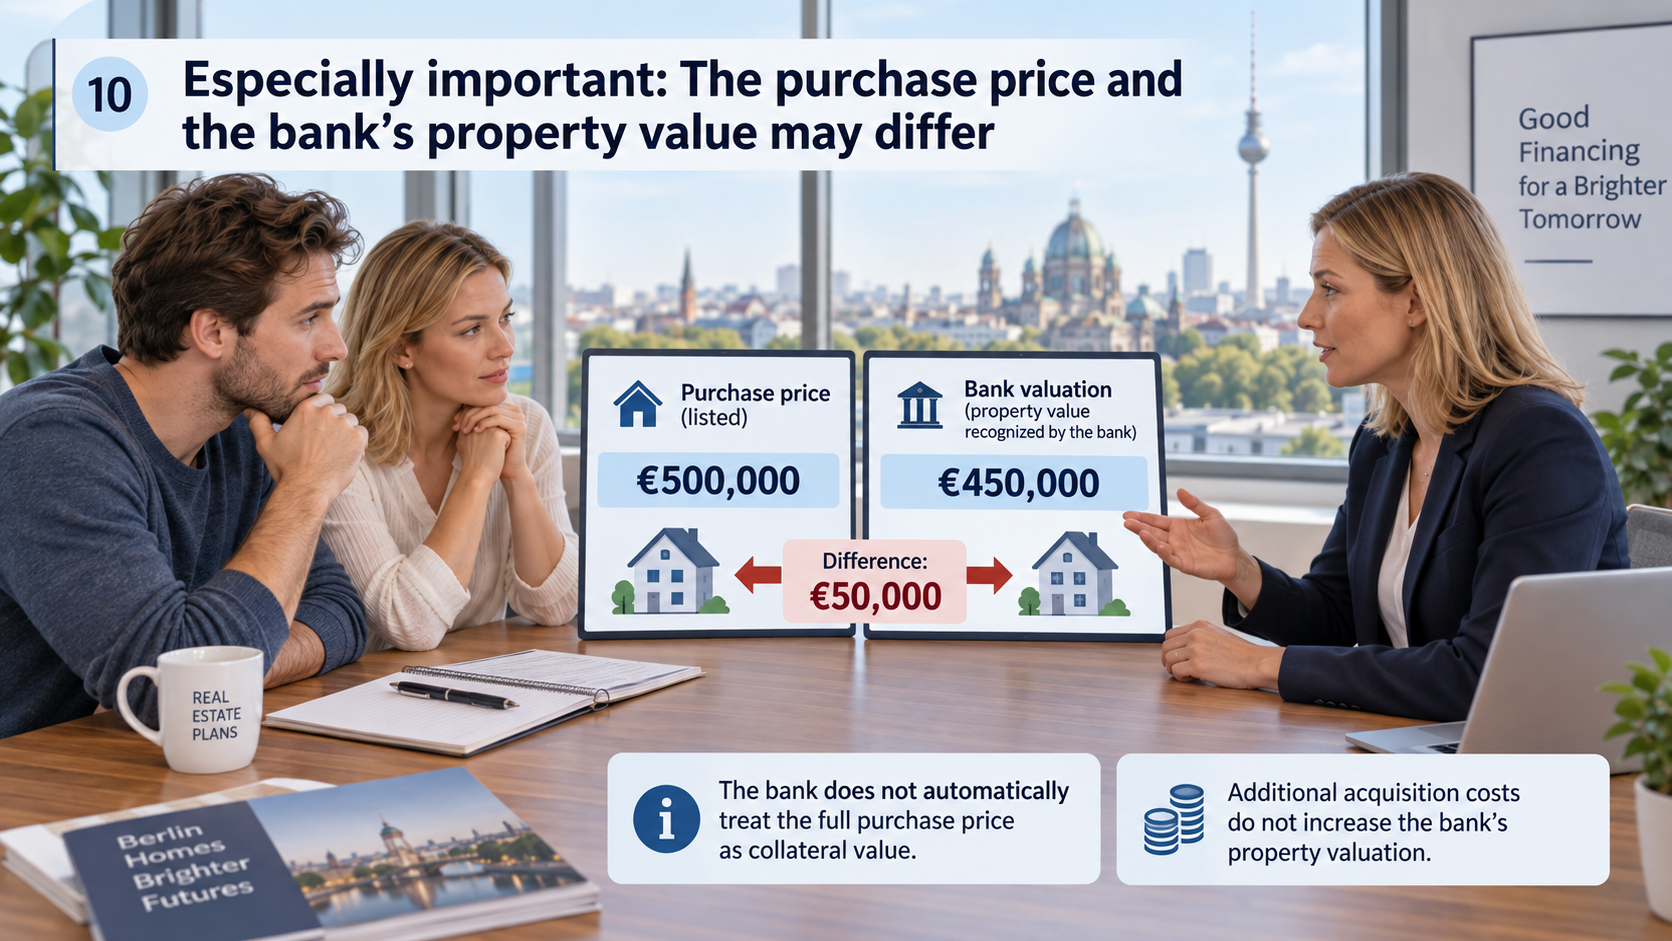
10. Especially important: The purchase price and the bank’s property value may differ
This point directly connects to the previous article.
Let us assume:
Purchase price: €500,000
But the bank values the property at only:
€450,000
The bank will not automatically treat the full €500,000 as collateral value.
If a loan of €450,000 is requested at the same time, then from the bank’s perspective, practically the entire value it recognizes as collateral is already being used to secure the loan.
The additional acquisition costs do not generally increase the bank’s assessment of the property value.
A €30,000 real estate transfer tax bill or a real estate agent commission does not make the property itself more valuable.
This is one of the reasons why sufficient equity can be so important in real estate financing.
Conclusion
For a property with a purchase price of €500,000 and bank financing of €450,000, it is not sufficient to calculate only the €50,000 difference.
In Berlin, significant additional costs arise, particularly from the 6% real estate transfer tax, notary and land register fees and, where applicable, real estate agent commission.
In our simplified example:
Without a real estate agent:
Purchase price: €500,000
Additional costs: approx. €37,500
= Total cost: approx. €537,500
With financing of €450,000:
Required own funds: approx. €87,500
With a real estate agent at an assumed 3.57% buyer’s share:
Total cost: approx. €555,350
With financing of €450,000:
Required own funds: approx. €105,350
The key question before buying a property is therefore not only:
“How much will the bank finance?”
but also:
“What are my total acquisition costs, and how much of my own capital do I actually need?”
Free Consultation
Have questions about entering the German market? Request a free consultation.
Request Free Consultation