Buying a property is one of the biggest financial decisions most people will make in their lifetime. This is why an important question arises for both buyers and sellers:
When can the financing of a property purchase be considered truly secure?
An initial financing confirmation from a bank is helpful, but it does not necessarily mean that the financing has been finally approved. Before making a binding credit decision, the bank will generally examine both the financial situation of the buyer and the property itself.
The more complete the documentation, the more efficiently and reliably the bank can assess the financing.
1. What does the buyer need for real estate financing?
First, the bank wants to determine whether the buyer will be able to make the monthly loan payments on a long-term basis.
For an employee, the bank will typically request documents such as:
Identity card or passport
Recent payslips
Employment contract or proof of employment
Bank statements
Proof of available equity
Information on existing loans, leasing agreements or other financial obligations
SCHUFA information or consent to a creditworthiness check
Where applicable, income tax documents
The bank does not look only at the buyer's monthly income. It examines the buyer's overall financial situation and calculates whether sufficient disposable income remains after living expenses and existing financial obligations to cover the future mortgage payment.
Permanent employment is an important factor
A regular and reliable income from permanent employment can make financing easier. From the bank's perspective, a long-term employment relationship with stable income is generally a positive factor.
However, a permanent employment contract alone does not automatically guarantee financing. The bank also considers existing loans, equity, monthly expenses and the amount of financing requested.
2. How important is SCHUFA?
The buyer's creditworthiness plays an important role in the bank's lending decision.
The bank wants to determine whether the buyer already has significant financial obligations and whether there are indications of payment difficulties. A creditworthiness check is therefore normally part of the financing process.
A good SCHUFA record can be an important component of a successful financing application, but it does not replace the bank's other assessments.
3. How much equity should the buyer have?
The buyer's available equity is also relevant to the bank.
Equity may include, for example:
Bank savings
Savings accounts
Securities
Building-society savings
Other verifiable assets
In many cases, it is advisable to finance at least part of the purchase price and the additional acquisition costs from the buyer's own funds.
The higher the equity contribution, the lower the amount that generally needs to be financed in relation to the property's value.
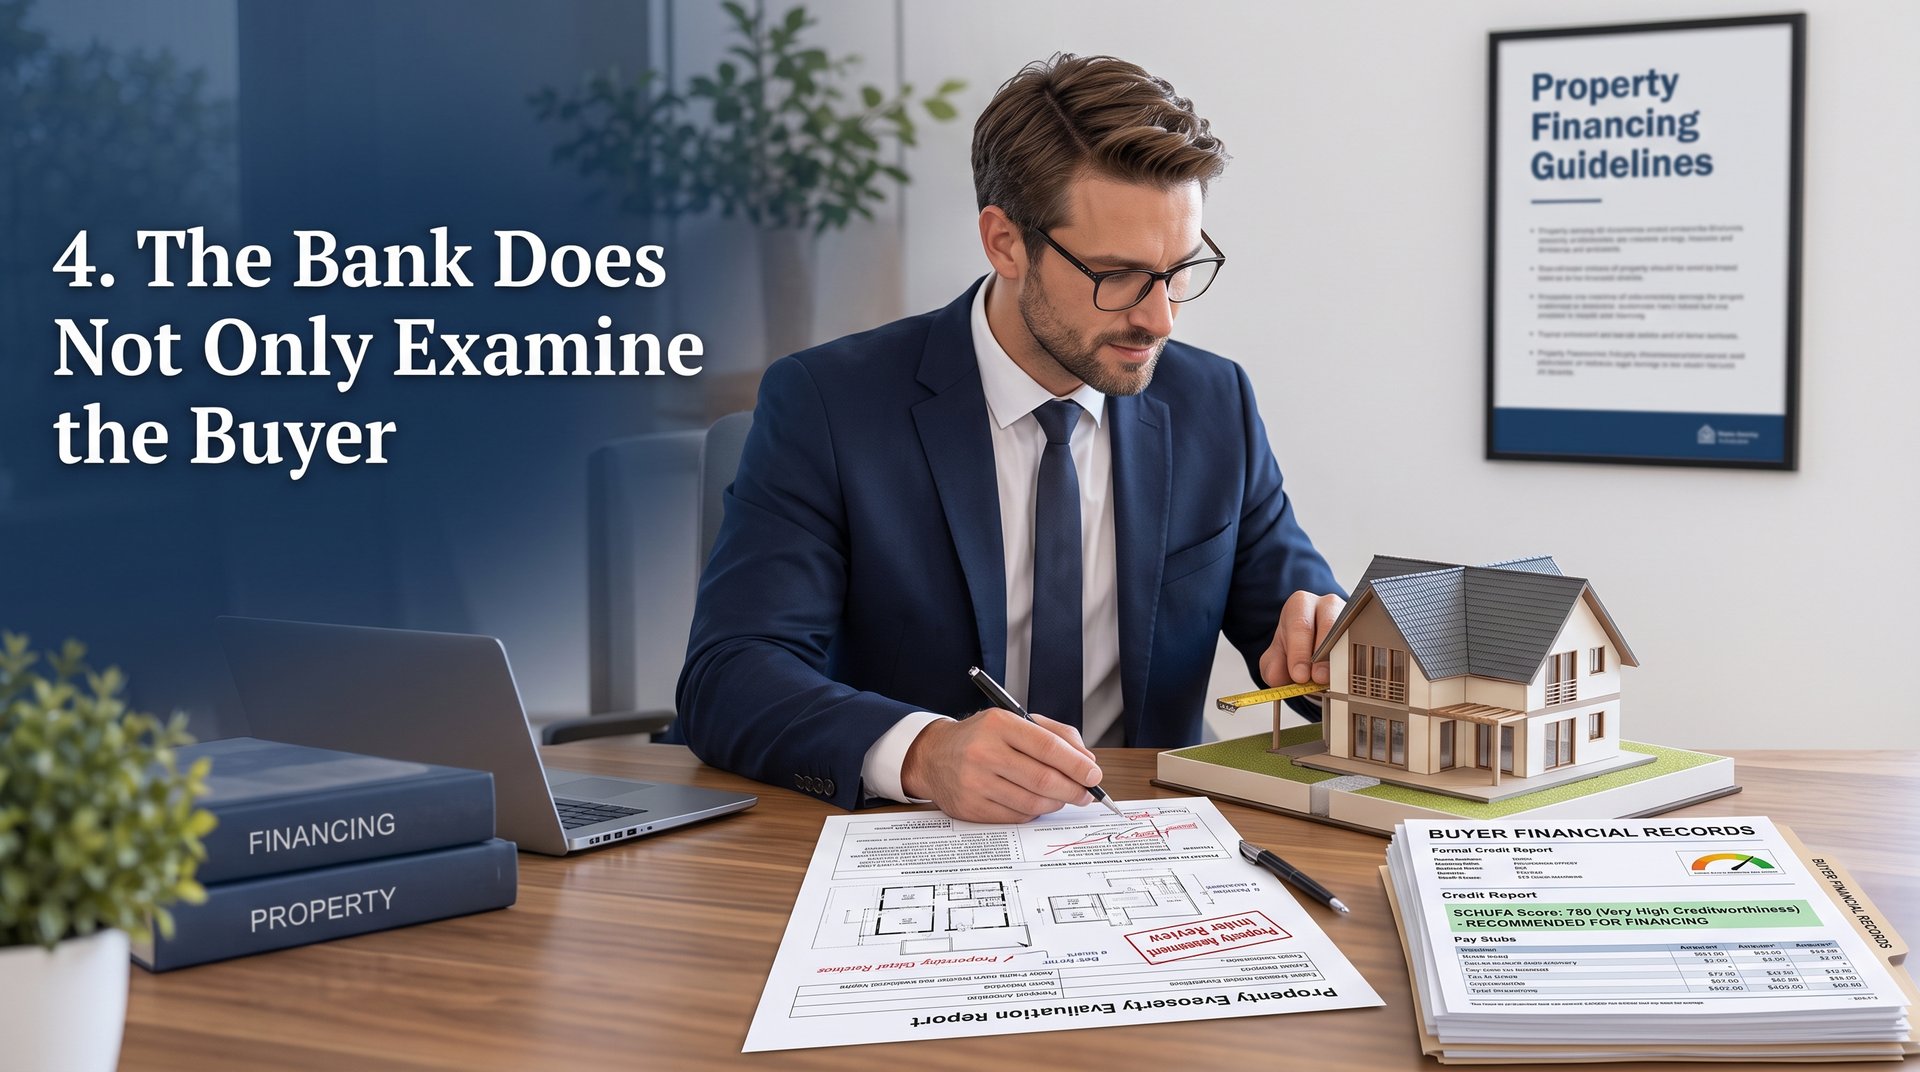
4. The bank does not only examine the buyer
This is a point that many buyers – and sometimes sellers – underestimate.
The bank does not automatically finance the purchase price stated by the seller.
The bank also examines the value of the property because the property serves as security for the loan.
For this purpose, the bank will typically require documents such as:
Current land register extract
Draft purchase agreement
Cadastral map or site plan
Floor plans
Calculation of living space
Property brochure or exposé
Photographs of the property
Energy performance certificate
Information about renovations and modernization
Where applicable, building specifications and other construction documents
These documents allow the bank to assess the property and identify potential legal or structural issues.
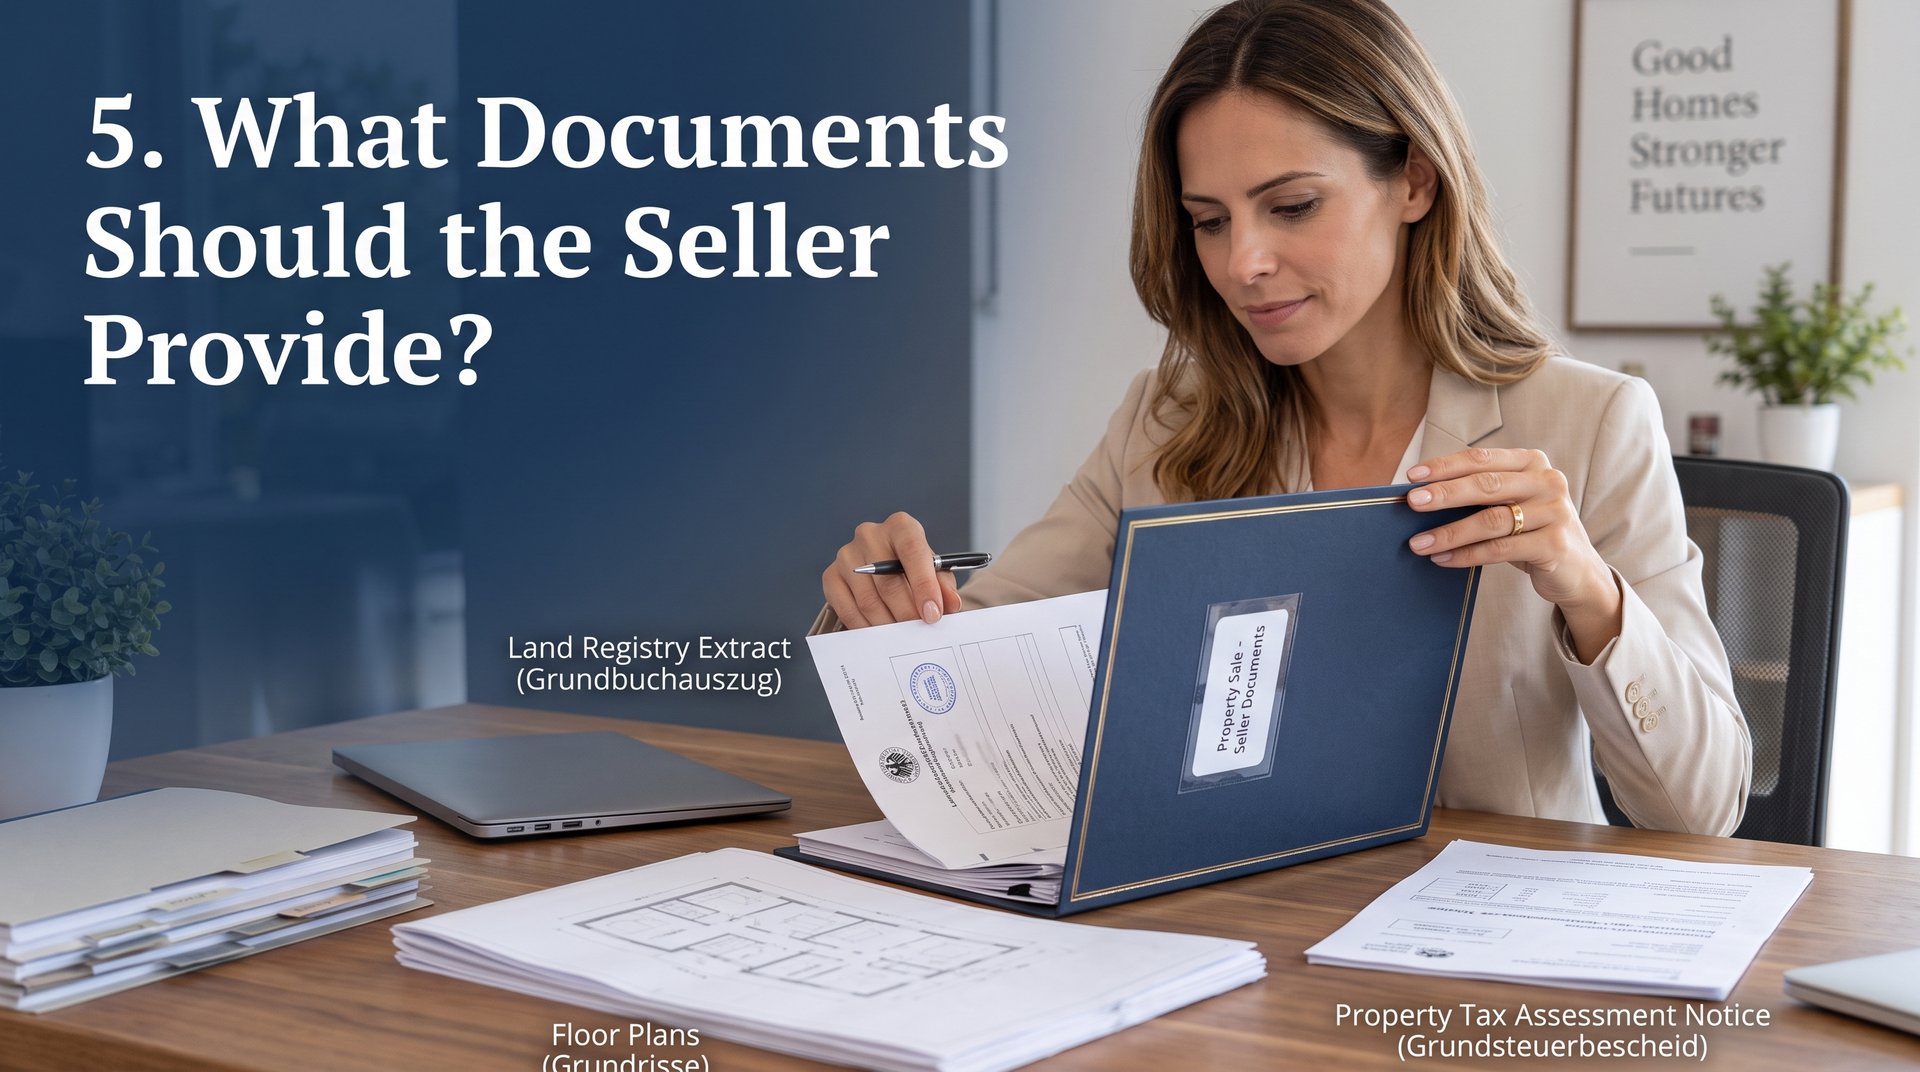
5. What documents should the seller provide?
The seller should ideally prepare a complete property documentation package as early as possible.
For a house, this may include:
Land and property
Current land register extract
Cadastral map or site plan
Information about the plot
Building
Floor plans
Living-space calculation
Building documents
Evidence of renovations and modernization
Energy performance certificate
Current photographs
Purchase
Purchase price
Draft purchase agreement
Information about existing charges or encumbrances
The current land register extract is particularly important because it allows the bank to identify existing rights, mortgages and other encumbrances affecting the property.
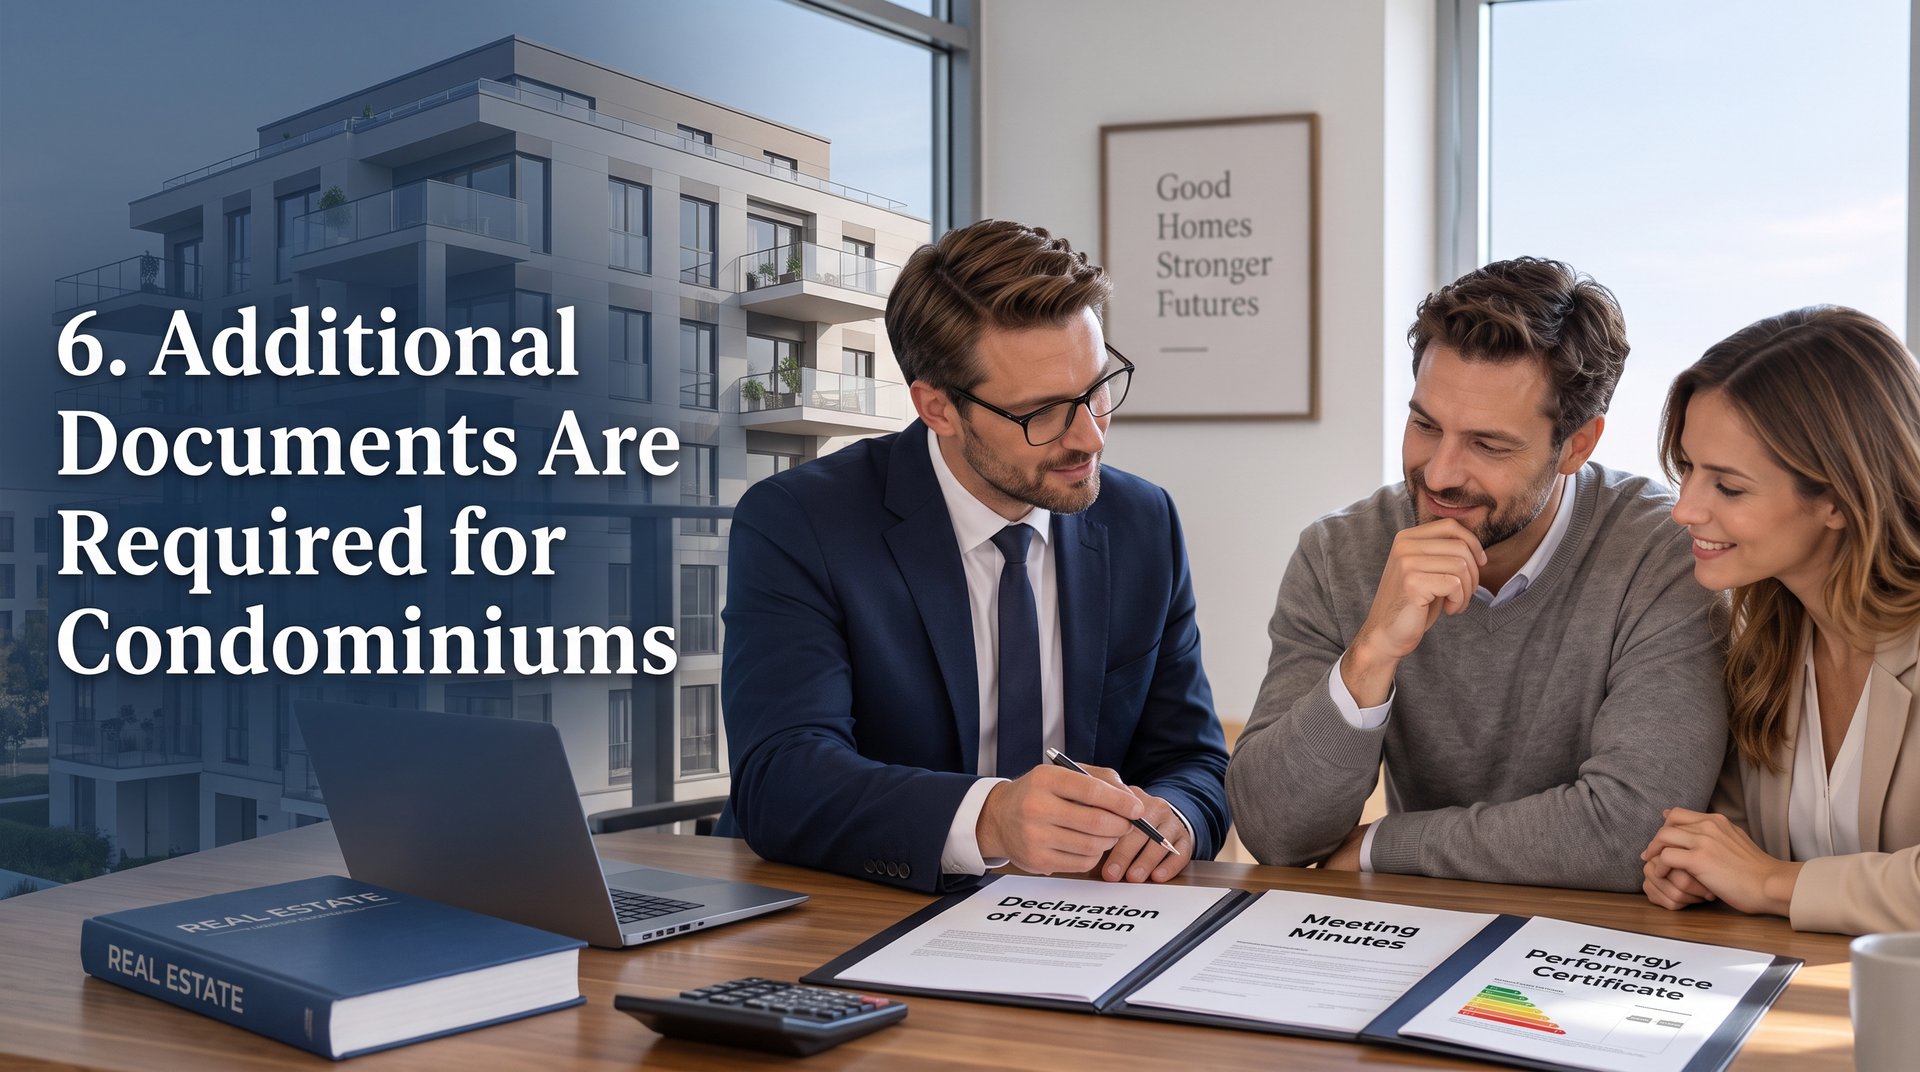
6. Additional documents are required for condominiums
When purchasing a condominium, the bank generally needs to examine not only the individual apartment but also the legal structure of the condominium ownership.
Additional documents may include:
Declaration of division
Allocation plan
Community rules
Information concerning the homeowners' association
Minutes of homeowners' meetings, where applicable
Information about monthly service charges and reserve funds
Again, the bank wants to know precisely what it is receiving as collateral.
7. Why can financing fail despite sufficient income?
A buyer may have a good and regular income and still fail to obtain final financing approval.
One possible reason is that the bank values the property lower than the agreed purchase price.
Example:
Purchase price:
€500,000
Property value considered by the bank:
€450,000
In such a situation, financing may become more difficult because the bank is assessing the property as collateral at a lower value.
The buyer may therefore need to provide additional equity.
This is why it is important not only to ask:
“Can I afford the monthly payment?”
but also:
“Is the property worth enough, from the bank's perspective, to support the requested financing?”
8. What does a financing confirmation actually mean?
It is important to distinguish between different types of financing confirmations.
An initial financing confirmation can show the seller that the buyer is generally capable of financing a property within a certain price range.
However, this does not necessarily mean that the bank has given its final approval.
For final financing approval, the bank normally also needs to review the specific property and its complete documentation.
The decisive factors are therefore:
Buyer assessment + property assessment + complete documentation + final credit decision
Only once these elements have been reviewed and the financing has been formally agreed is there a significantly higher level of certainty that the purchase can proceed as planned.
9. What should the seller consider before signing the purchase agreement?
For the seller, it can be useful to request more than a general statement such as:
“The bank will finance it.”
A specific financing confirmation or, where already available, a binding loan commitment from the financing bank provides considerably more clarity.
At the same time, the seller should provide all necessary property documents to the buyer and the bank as quickly and completely as possible.
Even a buyer with excellent creditworthiness may experience delays if important property documents are missing.
Conclusion
Real estate financing is essentially based on two pillars:
1. The buyer must be creditworthy.
This includes, in particular, regular income, sufficient financial capacity, a satisfactory creditworthiness assessment, available equity and manageable existing debt.
2. The property must be suitable as collateral.
For this purpose, the bank may require documents such as the land register extract, cadastral map, floor plans, living-space calculation, energy performance certificate, draft purchase agreement and other property documentation.
Buyers who prepare their personal financial documents in advance and sellers who provide a complete property documentation package can significantly facilitate the financing process.
Important: There is no absolute guarantee of financing approval before the bank has completed its review of all relevant documents and made its final credit decision. An initial financing confirmation should therefore not be confused with a binding loan commitment.
Free Consultation
Have questions about entering the German market? Request a free consultation.
Request Free Consultation